Apply for Loan EMI Calculator
Give us a Missed Call Pay EMI

Loan Default: What it means and how to recover successfully

Loan Default: Understanding Its Impact and Steps to Successful Recovery

Loan default can be a daunting financial setback; however, understanding its implications and knowing the steps to recovery can pave the way for Loan Default and its Successful Recovery, helping borrowers regain control of their finances. Whether it’s a mortgage, personal loan, or home finance, avoiding loan default is essential for maintaining long-term financial stability. For those already facing this challenge, exploring recovery options and understanding the benefits of overcoming default is the first step toward financial security.

What is Loan Default

Loan default occurs when a borrower fails to meet the repayment terms agreed upon with the lender. Defaults typically happen after several missed payments, and the consequences can be significant, ranging from severe damage to credit scores to the loss of valuable assets and potential legal action. For both borrowers and lenders, loan default represents a critical issue that requires immediate attention and resolution.

Read more: 10 Myths about Loan Against Property

Common Causes of Loan Default

  • Financial Instability: Unforeseen circumstances like job loss or medical emergencies often disrupt repayment schedules.
  • Overborrowing: Taking loans beyond your repayment capacity can lead to financial strain and eventual loan default.
  • Lack of Financial Planning: Poor budget management and irregular savings often result in missed payments and Loan Default.

Defaulting on a loan not only affects the borrower but also impacts the lender, as recovery costs and administrative burdens increase. Addressing these issues quickly is essential to minimize the consequences.

Steps to Recover Successfully from Loan Default

1. Assess Your Current Financial Situation
The first step to recovery is understanding your financial standing. Calculate your total income, expenses, and outstanding debts to determine the available resources for repayment.

2. Communicate With Your Lender
Contact your lender immediately after a default. Most financial institutions are willing to work with borrowers to create a feasible repayment plan or restructure the loan.

Options Your Lender May Provide
Loan Restructuring: Extending the repayment period or reducing monthly installments to ease the financial burden.
Forbearance: Temporarily pausing or reducing payments to provide breathing room during challenging times.

3. Explore Debt Settlement or Consolidation
For individuals managing with multiple loans, debt consolidation can simplify repayments by combining all debts into a single monthly payment. Alternatively, settlement negotiations can also reduce the total amount owed offering a manageable path to recovery.

4. Seek Professional Financial Advice
Financial advisors or credit counselors can provide valuable insights and help you create a sustainable plan for recovery. They often identify repayment strategies that borrower might overlook or key resource in overcoming defaults.

Benefits of Choosing the Right Home Loan

Choosing the right home loan can make a significant difference in avoiding loan default and ensuring financial stability.

Affordable EMIs: Well-structured repayment plans ensure affordability and reduce the risk of future.
Tax Benefits: Many home loans offer tax deductions, making them financially advantageous.
Asset Building: Real estate remains a stable investment option for appreciating asset in the future.

Read more: Down Payment on Home Loan

How to Avoid Loan Default in the Future

1. Create a Robust Financial Plan
Develop a budget that prioritizes loan repayments and savings. This ensures to have a better picture of your expenses and also prepare for uninvited expenses. Emergency funds can act as a buffer for unforeseen circumstances.

2. Borrow Responsibly
Ensure that loan amounts are within your repayment capacity. Carefully review loan terms and conditions including interest rates and repayment schedules before signing an agreement to avoid unexpected challenges.

3. Maintain Open Communication With Your Lender
In case of financial difficulties, inform your lender early. They may offer adjustments such as payment reductions to prevent the situation from escalating to default.

Conclusion

Loan default is a challenging situation, but with the right strategies, it’s possible to recover and build a stable financial future. From communicating with lenders to developing better financial habits, each step can help borrowers regain control. By resolving defaults, you unlock benefits such as improved credit, retained assets, and reduced stress. Vridhi Home Finance provides tailored home loan solutions for your housing needs, ensuring you can achieve your dreams with financial security. Explore our options today and take the first step towards homeownership.

What Credit Score Is Needed to Buy a House in India?

What Credit Score Is Needed to Buy a House in India? Latest Housing Loan Trends & Approval Insights

Buying a home in India is no longer just about income proof or property value. Today, your credit score plays a major role in determining whether your home loan gets approved, how much loan amount you receive, and even the interest rate you pay over the years.

According to recent reports by the Reserve Bank of India (RBI) and TransUnion CIBIL, more than 72% of retail loans approved in India are issued to borrowers with a credit score above 750. In the affordable housing sector, lenders are increasingly using credit behaviour and repayment history to assess risk before approving loans.

For first-time homebuyers, especially in Tier 2, Tier 3, and rural markets, understanding the importance of a credit rating has become essential before applying for a housing loan.

What is a Credit Score?

A credit score is a three digit number representation of your creditworthiness. Typically ranging from 300 to 900, it is calculated based on factors such as your repayment history, credit utilization ratio, length of credit history, types of credit, and recent inquiries. In general, higher scores indicate lower credit risk, which, in turn, increases your chances of loan approval.

Read more: Home Loan with low CIBIL Score

Why Credit Score Matters more in 2026?

India’s housing finance market has seen rapid growth over the last few years. As per National Housing Board (NHB) data, the housing loan portfolio in India crossed Rs.33 lak crore, with affordable housing contributing significantly to the demand. At the same time, lenders have become more cautious about repayment behavior due to rising retail credit exposure. This has increased the importance of credit asssessment during home loan approval.

What is considered a good score for Home Loan?

While every lender has its own eligibility criteria, industry trends suggest the following ranges are commonly considered during home loan processing:

Credit Score Range Loan Approval Possibility
750 & Above High approval chances with competitive interest rates
700 – 749 Generally acceptable for most housing loans
650 – 699 Approval possible, but stricter evaluation may apply
Below 650 Higher risk category for lenders

Many affordable housing finance companies also evaluate additional factors such as income stability, repayment capability, banking behaviour, and property profile — especially for self-employed and informal income applicants.

Common Reasons Why Home Loans Get Rejected

In many cases, loan rejection is not because of low income alone. Lenders also evaluate financial discipline and credit behaviour. Some common reasons include:

  • Frequent missed EMI or credit card payments
  • High existing debt obligations
  • Multiple loan enquiries within a short period
  • Irregular banking transactions
  • Errors in credit reports
  • Lack of formal credit history

For many borrowers, improving these factors early can significantly strengthen future home loan eligibility.

How to Maintain a Good Credit Score?

Ensuring a strong credit rating requires consistent effort and informed decisions. Therefore, below are key practices that will help you keep your credit rating in top shape:

1. Pay Bills on Time
Late payments can have a significant negative impact on your score. To avoid this, setting reminders or enabling auto-pay for bills ensures timely payments.

2. Keep Credit Utilization Low
The credit utilization ratio is the percentage of your credit limit that you use. As a rule of thumb, it is advisable to keep this ratio below 30%, as higher usage signals over-reliance on credit.

3. Monitor Your Credit Report Regularly
Errors in your credit report can adversely affect your score. Thus, review your credit report periodically and dispute inaccuracies to ensure its accuracy.

4. Avoid Excessive Credit Applications

Every credit application generates a hard inquiry, which can temporarily lower your score. Therefore, apply for credit only when necessary to avoid potential damage.

5. Maintain a Diverse Credit Mix
A mix of secured loans (e.g., home loans) and unsecured loans (e.g., credit cards) demonstrates your ability to handle various types of credit effectively.

6. Maintain Old Accounts
The length of your credit history contributes significantly to your rating. By keeping older accounts active, you can positively impact your creditworthiness.

Benefits of a Good Credit Score

Having a good credit report opens doors to financial opportunities and provides peace of mind. Below are the key benefits:

1. Easier Loan Approvals
Lenders are more likely to approve loans quickly when you have a good credit record, as it reflects low credit risk. As a result, you can get the funds you need faster.

2. Lower Interest Rates
Borrowers with high credit score enjoy favorable interest rates, which significantly reduces the cost of borrowing.

3. Higher Credit Limits
With a strong report, financial institutions may offer you higher credit limits, Therefore enhancing your purchasing power.

4. Better Credit Card Offers
Premium credit cards with higher rewards, lower fees, and better perks are often accessible to individuals with excellent credit rating Thus, you can benefit from greater financial flexibility.

5. Improved Negotiation Power
A good credit record can give you leverage to negotiate better loan terms, such as flexible repayment tenures or reduced processing fees. In turn, this can help you save money in the long run.

Read more: Personal Loan or Loan Against Property

Conclusion

Your credit score plays a key role in shaping your financial future and loan eligibility. By paying bills on time, keeping credit utilisation low, avoiding unnecessary loan or card applications, and monitoring your report regularly, you can steadily build a strong financial profile. A healthy score not only improves your chances of loan approval but also helps you secure better interest rates and greater financial flexibility. Ready to turn your strong financial profile into your dream home? Explore customised home loan solutions from Vridhi Home Finance and take the first step toward smarter homeownership today.

Frequently Asked Questions (FAQs)

1. What is a credit score and why is it important?

A credit score is a three-digit number that reflects your creditworthiness based on your repayment history and financial behaviour. It is important because lenders use it to evaluate your eligibility for loans and credit cards.

2. What is considered a good credit score for a home loan?

A credit score of 750 or above is generally considered good for securing a home loan. A higher score can improve your chances of approval and help you get better interest rates.

3. How can I improve my credit score quickly?

You can improve your score by paying EMIs and credit card bills on time, reducing credit utilisation, avoiding multiple loan applications, and regularly checking your report for errors.

4. Does checking my credit score affect my credit report?

No, checking your own credit score is considered a soft inquiry and does not negatively impact your credit report.

5. How does a low credit score affect loan approval?

A low credit score may reduce your chances of loan approval and could result in higher interest rates, lower loan amounts, or stricter repayment terms from lenders.


Which Loan is More Advisable: Personal Loan or Loan Against Property?

Which Loan is More Advisable: Personal Loan or Loan Against Property?

When faced with financial needs, choosing the right loan is crucial. Among the many options available, Personal Loans and Loans Against Property (LAP) are two popular choices. Each loan type serves different purposes and has unique benefits. This article explores both options to help you decide which is better suited for your financial needs.

Understanding Personal Loans

What is a Personal Loan?

A personal loan is an unsecured loan offered by financial institutions. It does not require collateral, making it ideal for short-term needs such as medical emergencies, weddings, or vacations.

Read More : Loan Against Property : Flexible Funds – Low Interest Rates


Which Loan is more advisable Personal Loan vs LAP?
More Advisable Personal Loan vs LAP?

Key Features of Personal Loans

  1. Quick Approval: Personal loans often have fast approval processes.
  2. No Collateral Required: Borrowers do not need to pledge any assets.
  3. Higher Interest Rates: Due to the lack of collateral, interest rates are generally higher.
  4. Flexible Usage: Funds can be used for a variety of purposes without restrictions.

Understanding Loan Against Property

What is a Loan Against Property (LAP)?

A loan against property is a secured loan where borrowers pledge their residential, commercial, or industrial property as collateral. This type of loan is suitable for larger financial needs like business expansion, higher education, or debt consolidation.

Key Features of Loan Against Property

  1. Lower Interest Rates: As it is secured by collateral, interest rates are lower than personal loans.
  2. Longer Tenure: Loan terms can extend up to 15-20 years, reducing monthly EMIs.
  3. Higher Loan Amounts: The loan amount depends on the property’s value, which is typically higher than unsecured loans.
  4. Restricted Usage: Funds are generally expected to be used for larger financial goals.

Comparison Between Personal Loans and Loan Against Property

  1. Loan Amount
  • Personal Loan: Ideal for smaller financial requirements, usually ranging between ₹50,000 to ₹25 lakhs.
  • Loan Against Property: Suitable for larger amounts, often exceeding ₹1 crore, depending on property valuation.
  1. Interest Rates
  • Personal Loan: Interest rates range between 10% to 24%, depending on creditworthiness.
  • Loan Against Property: Rates are lower, typically between 8% to 14%, as the loan is secured.
  1. Loan Tenure
  • Personal Loan: Shorter repayment periods, usually 1-5 years.
  • Loan Against Property: Longer repayment terms, up to 15-20 years.
  1. Approval Time
  • Personal Loan: Faster due to minimal documentation.
  • Loan Against Property: Longer processing time due to property valuation and verification.

Which Loan is More Advisable?

When to Choose a Personal Loan

  1. You need funds urgently and cannot provide collateral.
  2. Your requirement is for a smaller amount and a shorter tenure.
  3. You have a strong credit score and can manage higher EMIs.

When to Choose a Loan Against Property

  1. You require a substantial loan amount for long-term financial goals.
  2. You own property and are comfortable pledging it as collateral.
  3. You prefer lower EMIs and longer repayment tenures.

Explore More : 10 Myths about Loan Against Property – Busted!

LAP VS Personal Loan Affordable Home Loan

Factors to Consider Before Deciding

  1. Your Financial Goals

Evaluate the purpose of the loan. If it’s a short-term need, a personal loan may suffice. For long-term or larger investments, LAP is more practical.

  1. Your Repayment Capacity

Assess your monthly income, expenses, and financial commitments. Lower EMIs with LAP can be beneficial if you prefer affordability over a shorter tenure.

  1. Risk Appetite

Securing a loan with your property comes with risks. If you default on repayments, lenders could seize your property

Conclusion

Choosing between a personal loan and a loan against property depends on your financial needs and repayment capacity. Personal loans are ideal for short-term, smaller needs without collateral. On the other hand, loans against property offer lower interest rates and larger amounts but require property as security.

If you are unsure about which loan to choose, consult a financial advisor to understand your options better.

Vridhi Home Finance: Meeting Your Loan Needs

At Vridhi Home Finance, we provide a range of home loan solutions tailored to your needs. Whether you are planning to buy, build, or renovate a house, we are here to help. Contact us today to explore our offerings and make your financial goals a reality.


Property Tax: Basics, Calculation, and Benefits

Everything You Need to Know About Property Tax and How It’s Calculated

Owning a property brings pride, but it also comes with responsibilities. One of the most important ones is paying property tax. Many people treat it as just another yearly expense. However, it plays a key role in maintaining the infrastructure and services we rely on every day. When you understand how property tax works, you can plan your finances better, avoid penalties, and make smarter property decisions.

How to Pay "Property Tax"?

What is Property Tax and why do you need to be attentive?

Property tax is a yearly charge that local municipal authorities collect from property owners. Authorities calculate it based on the value of your property, including both the land and any structures built on it. The final amount depends on several factors. For instance, location, size, and usage (residential or commercial) all influence how much you pay.

It goes beyond a legal requirement. In fact, it directly affects your lifestyle and long-term investment. To begin with, it funds essential services such as roads, sanitation, water supply, and public infrastructure. Without these funds, cities would struggle to maintain basic facilities. Moreover, timely payment keeps your ownership records clean. As a result, you avoid penalties and build financial discipline over time.

Why is Property Tax Important?

It is critical for maintaining public services and infrastructure. Here are some reasons why it is important:

1. Revenue for Local Authorities
Property tax provides local governments with the funds needed to deliver essential services. Without it, the quality of services like garbage collection, water supply, and public transport would decline.

2. Supports Community Development
The revenue generated from property tax is reinvested into the community to build schools, hospitals, and recreational facilities. It helps improve living standards for all residents.

3. Encourages Responsible Ownership
Paying property tax reminds owners of their responsibilities towards society. It creates a sense of accountability for maintaining and utilizing property effectively.

How is Property Tax Calculated?

The calculation of property tax depends on various factors and formulas, which may vary from one location to another. However, the general process involves three key components:

1. Annual Rental Value (ARV) System
Authorities estimate how much rent your property could generate annually and calculate tax based on that value.

2. Capital Value System (CVS)
Here, authorities asses the market value of your property and apply a fixed percentage.

3. Unit Area Value (UAV) System
In this method, tax depends on the per-sq-ft rate set for your locality and property type.

Formula for Prop. Tax Calculation:

Property Tax = Base Value of Property × Built-up Area × Applicable Tax Rate

This formula may vary depending on local tax laws and valuation methods.

Explore More : What is NACH in housing finance?

Myths about Property Tax?

Factors Influencing Property Tax

Several factors affect the amount of property tax you need to pay:

1. Location
Properties in urban areas with better amenities are taxed higher than those in rural areas. The locality’s infrastructure and facilities also influence the tax rate.

2. Type of Property
Residential, commercial, and industrial properties are taxed differently. Commercial properties often attract higher tax rates due to their revenue-generating nature.

3. Age of Property
Older properties may receive depreciation benefits, reducing their taxable value. Conversely, new constructions may attract higher taxes initially.

4. Amenities and Facilities
Properties with modern amenities like elevators, swimming pools, or security systems may have higher tax liabilities compared to those with fewer facilities.

Methods to Pay Property Tax?

Paying property tax has become more convenient with the availability of online and offline options. Here’s how you can pay:

1. Online Payment
Most municipal bodies offer online portals. You simply enter your property details and complete the payment using digital methods.

2. Offline Payment
Alternatively, you can visit your local municipal office, fill out the required forms, and pay via cash, cheque, or demand draft.

Conclusion:

Property tax is more than a mandatory payment—it is a reflection of responsible homeownership and sound financial management. In the housing finance industry, timely payment strengthens property credibility, supports smoother loan processing, and safeguards long-term asset value. By staying compliant, homeowners not only protect their investment but also contribute to stronger infrastructure and better communities, creating a secure foundation for future growth.

10 Myths About Loans Against Property – Busted!

10 Myths About Loans Against Property – Busted!

Loans against property (LAP) are a popular financial product in the housing finance sector. These loans provide an excellent way to unlock the value of your property for various financial needs. However, despite their benefits, LAP continues to be surrounded by myths that create unnecessary confusion and hesitation among potential borrowers.

This article busts the top 10 myths about loans against property and provides clarity to help you make an informed decision.

Read More : How Self-Employed can can get a home loan?

Why consider a Loan Against Property?

What is a Loan Against Property?

A loan against property is a secured loan that allows you to borrow money by pledging your property as collateral. This can include residential, commercial, or even industrial properties, depending on the lender’s policies. The loan is versatile, allowing you to access significant funds for purposes like business expansion, debt consolidation, or even personal expenses.

Let’s debunk the most common myths surrounding LAP.

Myth 1: Only Residential Properties are Eligible

Fact:
One of the most common misconceptions is that only residential properties can be used as collateral. The reality is that lenders accept a wide range of property types, including commercial spaces, industrial properties, and even plots. The type of property does impact the valuation, but it does not limit your eligibility.

Myth 2: The Loan Amount Equals the Property’s Full Value

Fact:
Many believe that the loan amount equals the total market value of the property, but this is not true. Lenders offer loans based on the Loan-to-Value (LTV) ratio, which typically ranges from 50% to 75% of the property’s current market value. This ensures a safety margin for the lender while providing substantial funds to the borrower.

Myth 3: You Lose Ownership of the Property

Fact:
Pledging your property does not mean handing over ownership to the lender. You continue to own the property as long as you repay the loan as per the agreed terms. The lender only has a lien, which gives them the right to claim the property if repayments are not made.

Myth 4: Only Salaried Individuals Can Apply

Fact:
Loans against property are accessible to a wide range of individuals, including salaried employees, self-employed professionals, and business owners. While the documentation requirements may vary, LAP is not limited to salaried applicants. Lenders assess your repayment capacity based on your income source.

Myth 5: LAP is a Risky Option

Fact:
The perception of risk in LAP comes from the fear of losing the property. However, if you have a stable income and a solid repayment plan, LAP is a low-risk financing option. It offers lower interest rates and longer tenures compared to unsecured loans, making it a financially sound choice.

Myth 6: LAP Has High Interest Rates

Fact:
This myth often stems from confusion with unsecured loans like personal loans. Loans against property generally have lower interest rates because they are secured by collateral. The actual interest rate depends on factors like your credit score, loan amount, and lender policies.

Myth 7: LAP Processing is Time-Consuming

Fact:
While LAP processing involves property valuation and legal verification, advancements in digital banking have streamlined the process significantly. Many lenders now offer quick approvals, with minimal delays if all documents are in order.

Myth 8: Prepayment is Not Allowed

Fact:
Borrowers often assume that loans against property cannot be prepaid. On the contrary, most lenders allow partial or full prepayment, often with minimal or no charges. Prepayment can help reduce the total interest paid over the loan tenure.

Myth 9: Only Large Loan Amounts Are Offered

Fact:
Loans against property are flexible and can cater to varying financial needs. Whether you require a small amount for a personal expense or a large sum for business expansion, lenders provide loans tailored to your requirements. The loan amount depends on your property value and repayment capacity.

Myth 10: LAP is Only for Personal Use

Fact:
A significant advantage of LAP is its versatility. While you can use the loan for personal purposes, such as funding a wedding or education, it is equally suitable for business-related needs like purchasing equipment or expanding operations. The lender typically does not impose restrictions on the end use.

Explore More : Home Loan Top-Up : Key Facts & Benefits


How to apply for a Loan Against Property?
Loan Against Property? Myths vs Facts!

Why Consider a Loan Against Property?

Loans against property come with numerous benefits that make them a preferred choice for borrowers:

1. Flexible Tenures
Repayment tenures can extend up to 15-20 years, making EMIs manageable and reducing the financial burden.

2. High Loan Amounts
Unlock the potential of your property by availing substantial loan amounts to meet significant financial needs.

3. Competitive Interest Rates
LAPs offer lower interest rates compared to unsecured loans, ensuring affordable financing.

4. No End-Use Restrictions
Lenders allow borrowers to utilize the funds for any legal purpose, from personal expenses to business investments.

How to Apply for a Loan Against Property

Step 1: Evaluate Your Needs
Determine the exact amount you need and avoid over-borrowing.

Step 2: Check Your Credit Score
A higher credit score increases your chances of approval and better loan terms.

Step 3: Research Lenders
Compare loan offers from multiple lenders to find the best interest rate and terms.

Step 4: Prepare Your Documents
Ensure all required documents, such as property papers, income proof, and identity proof, are ready for submission.

Conclusion

Loans against property are an excellent financial solution for those seeking substantial funds at affordable rates. The myths surrounding LAP often discourage borrowers from exploring this option, but as we’ve clarified, most of these misconceptions are unfounded. By understanding the facts, you can make informed decisions and use your property as a powerful financial resource.

At Vridhi Home Finance, we offer tailored home loans to meet diverse needs. Whether you’re looking for a loan against property, a home construction loan, or other financing options, our team is here to help. Unlock your dreams with Vridhi Home Finance today!

NBFC Vs Bank: Choose the Best for Your Home Loan?

NBFC vs Bank: Which Is Better for Your Home Loan?

When you’re looking to secure a home loan, choosing between a Non-Banking Financial Company (NBFC) and a bank can be challenging. While both offer home loans, their approach, terms, and benefits differ significantly. NBFCs have emerged as a preferred option for many borrowers, offering flexibility, speed, and accessibility that traditional banks may lack. Let’s dive deeper to determine why NBFCs are often superior for home loans.

Understanding NBFC vs Bank

What Are NBFCs?

NBFCs are financial institutions that provide services similar to banks, such as loans and credit facilities, but operate under more flexible regulations. They focus on catering to borrowers who may not fit into traditional bank frameworks, making them more inclusive.

What Are Banks?
Banks are regulated financial institutions governed by the Reserve Bank of India (RBI). They offer a wide range of financial services, including savings accounts, loans, and deposits. However, their stringent lending policies and slower processes may limit their appeal to certain borrowers.

Read More : How to get construction loan?

         Key Differences between NBFC VS BANK?

Key Differences Between NBFCs and Banks

1. Eligibility Criteria
NBFCs: NBFCs are known for their relaxed eligibility norms. They lend to borrowers with lower credit scores, irregular incomes, or unconventional employment profiles like freelancers and small business owners.
Banks: Banks follow strict eligibility criteria, often rejecting borrowers who don’t meet their high credit score and income benchmarks.
Advantage: NBFCs open doors for borrowers who might otherwise struggle to secure loans.

2. Loan Processing Time
NBFCs: Known for quicker loan approvals, NBFCs process applications efficiently, requiring minimal documentation.
Banks: The approval process at banks involves extensive checks and verifications, leading to delays.
Advantage: NBFCs are ideal for borrowers seeking faster access to funds.

3. Customization of Loan Terms
NBFCs: NBFCs provide flexible repayment options and tailor loan products to suit individual borrower needs. They are more accommodating in restructuring loans or modifying terms.
Banks: Banks adhere to rigid repayment schedules and offer limited customization.
Advantage: NBFCs adapt better to individual borrower circumstances.

4. Interest Rates
NBFCs: While NBFCs may charge slightly higher interest rates than banks, they offer competitive deals for borrowers who don’t meet traditional criteria. For instance, they cater to self-employed individuals or those without formal income proof.
Banks: Banks generally offer lower interest rates but only to borrowers with strong credit scores and stable incomes.
Advantage: NBFCs make loans accessible for a broader audience, even at slightly higher rates.

5. Reach and Accessibility
NBFCs: With a stronger presence in semi-urban and rural areas, NBFCs excel at reaching underserved regions. They focus on financial inclusion, providing loans to borrowers in areas where banks may not operate.
Banks: Banks primarily focus on urban centers, limiting their availability in remote areas.
Advantage: NBFCs bring financial services to areas where borrowers may otherwise have no options.

Why NBFCs Are Superior for Home Loans

1. Borrower-Centric Approach
NBFCs prioritize customer satisfaction by providing personalized services. They ensure that borrowers have flexible repayment options, assistance with loan restructuring, and simplified processes.

2. Faster Loan Approvals
If you need a loan urgently, NBFCs are the better choice. They process applications quickly and disburse funds without the lengthy checks and balances that banks impose.

3. Accessibility for All Borrowers
NBFCs cater to individuals who don’t meet traditional lending standards, such as small business owners, freelancers, or those with irregular income. This inclusivity makes NBFCs the go-to option for many first-time homebuyers.

4. Simplified Processes
NBFCs focus on minimizing documentation and streamlining processes, making the loan journey smoother for borrowers. Unlike banks, they don’t bog borrowers down with complex procedures.

When Should You Choose NBFCs Over Banks?

  • If You Have a Low Credit Score: NBFCs are more likely to approve loans for borrowers with less-than-perfect credit histories.
  • If You Need Quick Disbursement: Their faster approval process is perfect for those seeking urgent funding.
  • If You Live in a Semi-Urban or Rural Area: NBFCs have a stronger presence in these regions.
  • If You Need Flexible Loan Terms: NBFCs customize loan products based on your needs.

Explore More : 10 Myths about Loan Against Property Busted!


Why Choose NBFC?
                   Why Choose NBFC?

Factors to Consider Before Choosing

1. Interest Rates
While NBFCs may charge slightly higher rates, they compensate with flexibility and accessibility. Compare the effective costs of loans between NBFCs and banks before deciding.

2. Loan Tenure
Choose the institution that aligns with your repayment capacity. NBFCs often allow longer repayment terms for borrowers needing lower monthly EMIs.

3. Service and Support
NBFCs excel in offering personalized customer service. Look for lenders that provide prompt responses and support throughout your loan tenure.

Conclusion

When it comes to home loans, NBFCs emerge as a superior choice for many borrowers. Their flexible eligibility criteria, faster approvals, and borrower-friendly approach make them ideal for individuals who face challenges meeting traditional bank requirements. Additionally, NBFCs excel at financial inclusion, serving semi-urban and rural populations effectively. While banks may suit borrowers with strong credit profiles, NBFCs cater to a much broader audience, ensuring that everyone has access to housing finance.

Vridhi Home Finance: Your Trusted NBFC for Home Loans
At Vridhi Home Finance, we specialize in offering tailored home loan solutions to meet your unique needs. Whether you’re buying, building, or renovating a home, we provide quick approvals, flexible terms, and competitive rates. Contact us today to make your homeownership dream a reality!

Economics of Eco-friendly Homes: A Smart Investment for Sustainable Future

Economics of Eco-Friendly Homes: A Smart Investment for a Sustainable Future

In recent years, eco-friendly homes—also known as sustainable homes or green housing—have been transforming the global housing market. The economics of eco-friendly homes is becoming a key focus due to their emphasis on sustainability, energy efficiency, and long-term cost savings. Modern homebuyers and property investors are increasingly drawn to these sustainable housing options because they combine financial benefits with environmental advantages. By reducing energy consumption, lowering utility costs, and increasing property values, eco-friendly homes offer a unique combination of financial rewards and environmental responsibility. This article explores the economics of eco-friendly homes, focusing on their cost-saving potential, sustainable living benefits, and long-term financial stability, making them a smart investment for homeowners and investors alike.

Why Eco-Friendly Homes Are Economically Viable

Eco-friendly homes rely on sustainable materials, energy-efficient systems, and water-saving technologies to minimize environmental impact and promote a sustainable lifestyle. While initially requiring a higher investment, green homes significantly reduce energy bills, improve property value, and decrease maintenance expenses, establishing their economic viability over time. For both homeowners and investors, this combination of financial and environmental returns creates a compelling case for choosing eco-friendly options.

Read more: Down payment Home Loans

Benefits of Eco-friendly Homes

Key Economic Benefits of Eco-Friendly Homes

Lower Energy Costs
A prominent economic benefit of eco-friendly homes is the significant reduction in energy consumption. These homes utilize solar panels, energy-efficient windows, and superior insulation to cut down on utility expenses. Though solar panels involve an upfront cost, they greatly lower monthly bills and, in some cases, generate additional income by selling excess power back to the grid.

Energy-Efficient Appliances
Eco-friendly homes feature energy-efficient appliances, LED lighting, and smart thermostats to minimize power usage. While these upgrades may require initial expenses, they yield ongoing savings, particularly as utility costs increase.

Increased Property Value
Sustainable home features enhance overall property value and attract eco-conscious buyers. With the demand for green housing rising steadily, eco-friendly homes have strong resale potential. Buyers increasingly seek properties offering financial and environmental savings, leading to higher demand for homes with sustainable amenities.

Government Incentives for Green Homes
A key economic advantage of eco-friendly housing is the availability of government support. Tax incentives, rebates, and subsidies make green home improvements more affordable by offsetting some of the initial costs. Moreover, energy-efficient homes often qualify for property tax reductions, allowing homeowners to save on multiple fronts.

Reduced Maintenance and Utility Costs
Eco-friendly homes are constructed with durable, high-quality materials, which require less maintenance and upkeep. Additionally, many green homes feature water-saving innovations like rainwater harvesting, which further reduces utility costs, especially in areas with elevated water rates.

Water-Saving Technologies
With the inclusion of low-flow fixtures, rainwater harvesting systems, and greywater recycling, eco-friendly homes can reduce water usage and costs. This is especially advantageous for properties located in regions experiencing water scarcity, as these technologies help cut both consumption and utility expenses.

Healthier Living Environment
Eco-friendly homes contribute to healthier living by using non-toxic materials that promote improved indoor air quality. Low-VOC paints, non-toxic adhesives, and other safe materials reduce indoor pollutants, supporting respiratory health and overall wellness for residents.

Lower Carbon Footprint
Eco-friendly homes significantly lower their carbon footprint using renewable energy and efficient systems. Reducing dependency on fossil fuels helps decrease greenhouse gas emissions, aligning households with global climate objectives.

Long-Term Financial Benefits
Although green homes may require a higher upfront investment, they yield considerable financial benefits in the long run. Reduced utility bills, increased property values, and tax incentives provide homeowners with savings that can outpace those seen in traditional housing options.

Future-Proof Investment
Eco-friendly homes are built with adaptability in mind, designed to withstand resource challenges and changes in energy availability. These homes provide stability against rising energy costs and regulatory shifts, offering homeowners long-term financial security as part of their sustainable investment.

Financial Advantages over traditional Home
Financial Advantages Over Traditional Homes

Financial Advantages Over Traditional Homes

Traditional homes may have lower initial costs; however, eco-friendly homes bring substantial long-term financial benefits that become evident over time. From tax breaks to energy savings and increased property values, eco-friendly homes consistently outperform conventional properties in economic terms, positioning them as a forward-thinking choice for investors and homeowners focused on both financial and environmental gains.

Comparison of Eco-Friendly and Conventional Homes

  • Initial Investment: Though green homes involve a higher initial cost, they deliver considerable long-term savings through energy-efficient systems and reduced maintenance needs.
  • Monthly Savings: Utility costs are significantly lower in eco-friendly homes, creating ongoing financial benefits and security.
  • Property Value: Homes with sustainable features command higher resale prices due to increasing demand for eco-conscious housing.

Read more: Home Loan Top-Up

Conclusion

The economic advantages of eco-friendly homes make a compelling case for homeowners and investors. Eco-friendly homes offer financial savings, increased property values, and long-term sustainability benefits that extend well beyond their initial cost. As green technology advances and environmental awareness grows, eco-friendly homes are set to become the standard in sustainable housing, providing both economic and ecological benefits. For those seeking to invest in properties with a purpose, eco-friendly homes offer a truly rewarding opportunity. Vridhi Home Finance is committed to supporting your sustainable housing journey by offering various home loan options. Whether building, buying, or renovating, Vridhi Home Finance is here to assist in making your eco-friendly dream home a reality.


Home Loan Top-Up : Key Facts and Benefits

What is a Home Loan Top-Up? What are the benefits?

A home loan top-up is an additional loan amount offered by your existing lender on your current home loan. It is a convenient financial solution for individuals who require extra funds for purposes such as home renovation, medical emergencies, education, or business expansion. This article explores what a home loan top-up is, how it works, and its various benefits.

Understanding a Home Loan Top-Up

A home loan top-up allows borrowers to access extra funds over and above their ongoing home loan. It is usually granted to borrowers with a good repayment history and sufficient equity in their property. Unlike personal loans, a top-up loan typically comes with lower interest rates and a longer repayment tenure.

This facility is available only to existing home loan borrowers, making it an attractive option for those who need funds without applying for a new loan.

Read More : Cersai Charges

Home Loan - Top Up Benefits
Home Loan – Top Up Benefits

To understand how a top-up loan works, let’s consider an example. Assume you have an outstanding home loan of ₹20 lakhs, and your property is currently valued at ₹50 lakhs. If your lender permits a loan-to-value (LTV) ratio of 70%, you can borrow up to ₹35 lakhs, including the existing loan amount. This means you are eligible for a top-up of ₹15 lakhs.

Steps to Apply for a Top-Up Loan

  1. Check Eligibility: Contact your lender to confirm your eligibility for a top-up loan.
  2. Submit Documents: Provide any required documents, such as income proof or updated property valuation.
  3. Approval Process: The lender assesses your repayment capacity and outstanding loan balance.
  4. Disbursement: Once approved, the top-up amount is credited to your account.

Key Benefits of a HL Top-Up

A home loan top-up offers multiple benefits, making it a preferred choice over other loan options.

1. Lower Interest Rates

Top-up loans generally have lower interest rates compared to personal loans or credit cards. Since the loan is secured against your property, lenders offer competitive rates, reducing your overall borrowing cost.

2. Flexible Usage

Unlike a home loan, which must be used strictly for purchasing or constructing a property, a top-up loan can be used for a variety of purposes, such as:

  • Home renovation or repairs
  • Business expansion
  • Medical expenses
  • Educational needs

3. Longer Repayment Tenure

A top-up loan typically offers a longer repayment tenure compared to personal loans. This feature reduces your monthly repayment burden and provides financial flexibility.

4. Quick Processing

Since the lender already holds your financial and property details, the processing time for a top-up loan is much shorter. This quick turnaround makes it an ideal option for urgent financial needs.

5. Tax Benefits

In some cases, you may be eligible for tax benefits on the interest paid on a top-up loan if the funds are used for home renovation or construction. Consult your tax advisor for detailed guidance.

Explore More : What is Home Loan EMI ? How to calculate it?

Eligibility Criteria for Home Loan Top Up

Eligibility Criteria for a Home Loan Top-Up

While the criteria may vary between lenders, here are the common requirements:

1. Good Repayment History

Lenders prefer borrowers who have made consistent, timely EMI payments on their existing home loan. A strong repayment track record increases your chances of approval.

2. Sufficient Property Equity

Your property’s market value and the outstanding loan amount determine your eligibility. Sufficient equity in the property ensures that the lender’s risk is minimized.

3. Stable Income Source

Having a steady income stream assures the lender of your repayment capability. Ensure you can demonstrate your income stability through bank statements or salary slips.

Key Points to Consider Before Opting for a Loan

Before applying for a top-up loan, keep the following factors in mind:

1. Loan Tenure and EMI

Evaluate the loan tenure and EMI amount to ensure they fit within your budget. Longer tenure may reduce monthly payments but increase the total interest cost.

2. Interest Rate Comparison

Compare the top-up loan interest rates with other loan options to determine the most cost-effective solution for your needs.

3. Purpose of the Loan

Define the purpose of the loan clearly to avoid unnecessary borrowing. This ensures that you use the funds responsibly and efficiently.

4. Tax Implications

Consult a tax advisor to understand whether you can avail of tax benefits based on your intended use of the funds.

Differences Between a Top-Up Loan and a Personal Loan

Both top-up loans and personal loans serve various purposes, but they differ in several aspects.

Aspect Top-Up Loan Personal Loan
Interest Rate Lower Higher
Repayment Tenure Longer Shorter
Approval Time Faster Relatively Slower
Tax Benefits Available (in specific cases) Not Available

 Conclusion: A Smart Financial Choice

A home loan top-up is a smart financial option for borrowers looking to access additional funds at lower interest rates. With its flexible usage, longer tenure, and quick processing, it offers a range of benefits to meet diverse financial needs. However, it’s crucial to assess your financial situation and repayment capacity before opting for this facility.

Vridhi Home Finance offers flexible home loan top-up solutions tailored to your unique requirements. Contact us today to explore how we can help you achieve your financial goals!

Affordable Green Homes : Benefits and features

Affordable Green Homes: Where Smart Living Meets Savings

In today’s fast-paced world, affordable green homes have shifted from being a fleeting trend to a fundamental lifestyle necessity. As the push for sustainability gains momentum, property buyers are prioritizing eco-friendly housing options that align with their environmental values while remaining cost-effective. These homes strike a harmonious balance between energy-efficient designs and financial practicality, catering to the needs of the modern homeowner.

Adopting sustainable living solutions is no longer optional—it’s a wise investment in the future. From renewable energy integration to low-carbon construction materials, affordable green homes are designed to minimize environmental impact and maximize savings. With features like solar panels, rainwater harvesting systems, and energy-efficient appliances, these homes reduce utility bills while promoting ecological well-being.

For prospective buyers, investing in these eco-friendly properties is about more than just saving money; it’s about embracing a lifestyle that values both the planet and personal wellness. So, what sets these homes apart, and why are they the perfect choice for conscious homeowners? Let’s explore the unique benefits, innovative designs, and long-term advantages that make affordable green homes a standout choice in sustainable real estate.

What Are Affordable Green Homes?

Affordable green homes are residential properties designed with the goal of minimizing their environmental impact without sacrificing comfort or affordability. These homes are built using sustainable materials and energy-efficient technologies that not only reduce energy consumption but also enhance the quality of life for their residents. From solar power systems to rainwater harvesting solutions and energy-efficient appliances, green homes combine modern eco-friendly innovations with cost-effective building practices to make sustainable living within reach for more people.

Read More: Economics of Eco-friendly Homes

Key Features of Affordable Green Homes

Key Features of Affordable Green Homes

To enjoy the full benefits of an affordable green home, focus on the following features:

1. Energy Efficiency

Energy-efficient designs are the foundation of green homes. Features like LED lighting, programmable thermostats, and insulated windows dramatically reduce energy usage.

Pro Tip: Use a smart energy management system to monitor and optimize energy consumption.

 2. Renewable Energy Sources

Installing solar panels, wind turbines, or geothermal systems can further reduce reliance on non-renewable energy. While these systems may require an upfront investment, many governments offer tax credits and incentives to offset costs.

3. Water Conservation

Conserve water with features like low-flow toilets, rainwater harvesting systems, and drought-resistant landscaping. These upgrades significantly reduce water consumption and lower your bills.

4. Sustainable Building Materials

Choose eco-friendly materials such as bamboo, reclaimed wood, and recycled steel. These materials are durable, stylish, and environmentally responsible.

Benefits of Affordable Green Homes

Benefits of Affordable Green Homes

Affordable green homes offer a unique combination of cost savings, sustainability, and an improved quality of life. Designed with eco-friendly practices and efficient technologies, these homes provide numerous advantages for both homeowners and the environment. Let’s dive deeper into why investing in an affordable green home is a smart and sustainable choice.

  • Cost Savings

Energy-efficient appliances and systems significantly lower monthly utility bills. For instance, installing solar panels or energy-efficient HVAC systems can reduce electricity costs by up to 30%, helping homeowners save money while conserving energy.

  • Positive Environmental Impact

Affordable green homes help reduce your carbon footprint. By using renewable energy sources and sustainable materials, such as reclaimed wood or bamboo, these homes minimize reliance on non-renewable resources, making them a truly eco-conscious choice.

  • Enhanced Health and Comfort

Green homes promote healthier living through improved indoor air quality, non-toxic materials, and better ventilation. Insulated walls and windows also ensure year-round comfort, providing consistent temperature control in every season.

  • Higher Resale Value

Homes with green features are increasingly in demand. Buyers prioritize properties offering long-term savings, environmental benefits, and modern aesthetics. Investing in an affordable green home not only supports the planet but also increases your property’s market value.

Read More: Home Construction Loan

Why Affordable Green Homes Are the Future

The need for affordable green homes has never been greater. Climate change, rising energy costs, and the push for sustainability make them an essential part of the housing market. These homes provide a cost-effective way to reduce your environmental impact while creating a healthier and more sustainable planet.

Conclusion

Affordable green homes offer a practical, cost-effective solution for embracing eco-friendly living. These homes reduce utility bills, enhance comfort, and promote environmental sustainability. By making small upgrades and utilizing available incentives, you can create a greener home without overspending. Vridhi Home Finance offers flexible financing options tailored to sustainable housing. Let Vridhi help you turn your dream of owning an affordable green home into reality. Explore their offerings today and take the first step toward a brighter, greener future!

Buying V/S Renting a Home: How to choose your living solution

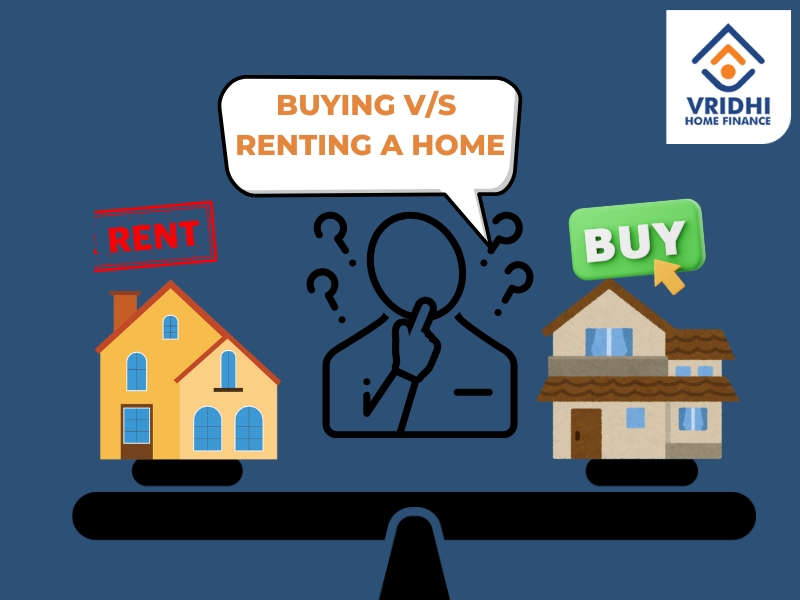
Buying V/s Renting a Home: Which is Right for You?

Buying V/S Renting a Home is a choice that shapes not only where you live but how you live. Owning a home offers stability and the pride of ownership, while renting brings flexibility and freedom. Deciding between the two depends on your financial situation, lifestyle preferences, and long-term goals. In this article, we’ll explore the advantages and challenges of Buying V/S Renting a Home to help you make the right decision for your unique needs.

What Does Buying a Home Involve?

Buying a home is a significant financial commitment; however, it comes with its own set of advantages. For instance, owning a home allows you to build equity over time, which can be a valuable asset as it provides a sense of stability and permanence that renting simply cannot offer. In addition, homeowners often benefit from tax deductions, such as mortgage interest and property taxes, which can reduce overall financial burdens. That said, while buying a home offers these long-term benefits, it also comes with challenges, such as high upfront costs and maintenance responsibilities. Therefore, it’s essential to carefully weigh the pros and cons before making such a substantial investment.

Read More: Pradhan Mantri Awas Yojana

Benefits of Buying a Home

  • Long-term Investment: Owning a home often builds equity over time. Real estate is generally considered a stable investment that appreciates in value.
  • Sense of Ownership: Buying a home provides a sense of stability and pride, allowing homeowners to customize and renovate to reflect personal tastes.
  • Tax Benefits: Homeowners may qualify for deductions on mortgage interest and property taxes, reducing the overall financial burden.
  • Stability for the Future: Fixed mortgage rates mean predictable monthly payments, providing financial stability compared to fluctuating rental prices.

Challenges of Buying a Home

While buying has its perks, it is essential to understand the drawbacks:

  • High Initial Costs: Down payments and closing costs can be significant.
  • Maintenance Responsibilities: Repairs and upkeep are the homeowner’s responsibility.
  • Limited Flexibility: Selling a home is time-consuming and can tie you to a location.

Perks and Pitfalls of Renting a Home

Renting a home offers flexibility, especially for those who move frequently. It involves lower initial costs, requiring only a security deposit and rent, making it more accessible than buying. Additionally, landlords handle maintenance, reducing responsibilities, while tenants enjoy the freedom to relocate easily.

1. Lower Initial Costs
Unlike buying, renting doesn’t require a down payment. A security deposit and initial rent are the primary upfront costs, making it more accessible.

2. Minimal Maintenance Responsibilities
Landlords typically handle repairs and maintenance in rental properties. This reduces your responsibilities and expenses.

3. Greater Flexibility
Renting allows you to move more easily. This is particularly advantageous for those who expect to relocate frequently due to work or lifestyle changes.

The Downsides of Renting a Home

While renting offers flexibility, it has its limitations which involves:

1. Lack of Equity
Rent payments don’t build equity. At the end of your lease, you have no financial asset to show for your housing expenses.

2. Limited Control
In a rental, you’re subject to your landlord’s rules. Personalizing or modifying the space may not be allowed.

3. Rent Increases
Rental costs can rise over time, potentially straining your budget. Unlike fixed-rate mortgages, rent hikes are common and unpredictable.

Read More: Home Loan Closure

Buying vs. Renting a Home: Key Factors to Consider

Deciding between buying and renting a home comes down to several factors that align with your personal situation.

Financial Stability
Buying requires financial readiness, including savings for a down payment, loan eligibility, and long-term income stability.
Long-Term Plans
If you plan to stay in one place for 5-7 years or more, buying may be the smarter financial decision.
Renting is better for short-term living situations or those uncertain about their future plans.
Market Conditions
Understanding the real estate market in your area is essential.

Conclusion

Ultimately, the decision to buy or rent depends on various factors, including your lifestyle, finances, and long-term goals. Buying a home, for instance, offers stability, equity, and a profound sense of ownership, making it an excellent choice for long-term planners. Conversely, renting provides flexibility, lower upfront costs, and the freedom to relocate, which is particularly beneficial for those with short-term living needs or uncertain circumstances. For those who are leaning toward homeownership, Vridhi Home Finance is here to help. With tailored home loan solutions designed to fit your unique requirements, we make your dream of owning a home a reality. Whether you are purchasing your first home or investing in a dream property, our flexible loan options ensure that your financial needs are met. Choose Vridhi Home Finance today and take the first step toward securing your own home!